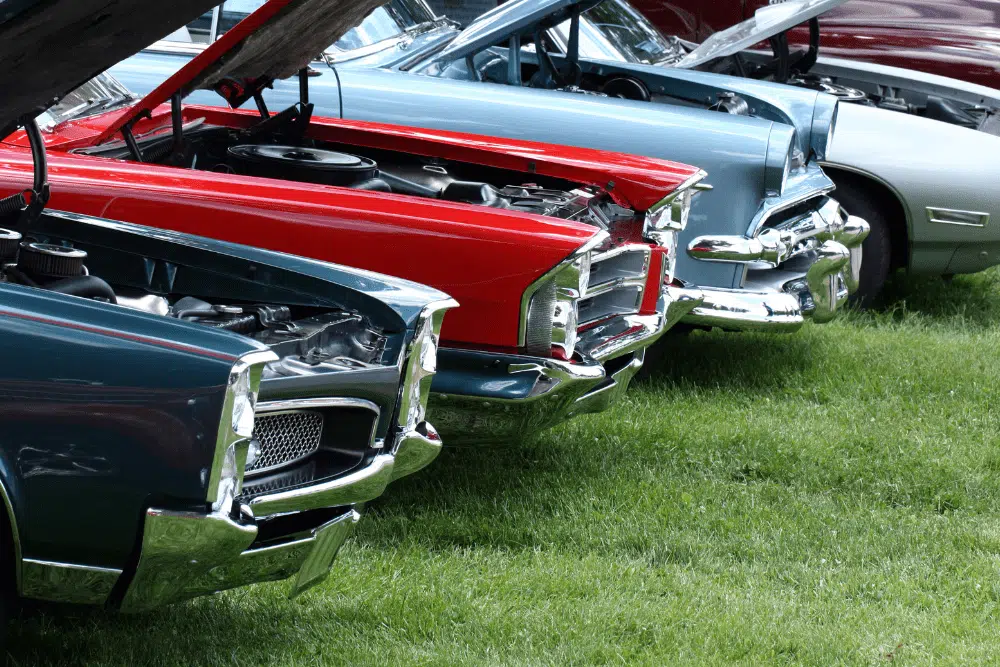
Buying a classic car is a dream for plenty of Australians, but financing one isn’t as simple as applying with your bank. Most lenders won’t touch a car past 15 to 20 years old, which is where classic car loans come in.
At Savvy, we work with more than 40 lenders, including specialists who finance classic, vintage and veteran cars. That means more choice than going straight to a lender and placing your application in the hands of someone who understands qualification criteria back to front.
What is a classic car loan?
A classic car loan is a type of finance for older, collectible vehicles that standard car loans won’t cover. There’s no upper age limit on the car, so it suits eligible vehicles that fall outside the usual 10- to 15-year cap.
Lenders usually count a car as classic once it’s over 30 years old. Some also include restored, imported and muscle cars. They’re generally treated as collectibles rather than daily drivers, used for display and the odd weekend drive.
Classic car loans work much like standard car loans:
- Secured: the loan is secured against the car, so you can’t sell it without paying out the loan
- Fixed rates: interest rates are typically fixed for the duration of the loan
- Loan terms: terms generally run from one to five years, with some lenders offering up to seven
The differences are in the lending criteria:
- No age limit: lenders don’t set a maximum age for the car
- Higher rates: interest rates may be higher than on a standard car loan
- Credit requirements: lenders may look more closely at your credit score and history
- Valuation: a professional valuation may be required
Not all lenders offer classic car finance, so working with a specialist or broker can help you find a suitable option.
What cars can I buy with a classic car loan?
Classic car loans cover a wide range of vehicles, from century-old veterans to muscle cars and imports. Lenders set their own rules, but cars are generally grouped by era:
- Veteran: built before 1919
- Vintage: built from 1919 to 1930
- Post-vintage: built from 1931 to 1949
- Classic acceptance: built from 1950 to 1969
- Modern classic: built from 1970 to 1989
Some lenders also consider younger cars that are rare or sought after, such as limited-run performance and imported models. Muscle cars, restored vehicles and imports are also commonly financed, whatever their age.
These groups come from Australian car clubs and government registration rules, and the details vary between states. A car that counts as a classic to a club may not qualify under a lender’s criteria, so check before you start shopping.
You can buy through a dealer, a private seller or an auction. Some lenders finance private sales and auction purchases, so it’s worth confirming this before you bid.
How lenders value a classic car
Standard used car pricing guides don’t always cover classic cars, so lenders often ask for a professional valuation.
A valuer looks at:
- Overall condition, such as bodywork, mechanical state and any restoration work
- How rare it is, such as how many were built and how many survive
- How much of the car is factory original
- How much collector appeal or general demand there is for the model
The valuation matters because the loan is secured against the car. If it comes in below the purchase price, you may be able to borrow less than you expected. Ask your consultant which valuers your lender accepts before you book one.
How much do classic car loans cost?
The cost of a classic car loan depends on a range of factors specific to you and the car you’re buying, including:
- Interest rate: the rate you’re offered, based on your credit profile, income, the car and the type of loan
- Loan amount: the more you borrow, the more interest you pay
- Loan term: a longer term lowers your repayments but costs more in interest overall
- Deposit: a larger deposit means borrowing less, which cuts interest and can help your rate
- Balloon payment: a lump sum at the end of the loan lowers your repayments but means paying more interest overall
- Fees: establishment, ongoing account and early exit fees vary between lenders
The loan term is one of the easiest to see in action. You can see in the table below how much more or less you might end up paying as a result of your loan term decision:
| Loan term | Monthly repayment | Total interest | Total repaid |
|---|---|---|---|
| 3 years | $1,046 | $7,666 | $37,666 |
| 4 years | $841 | $10,391 | $40,391 |
| 5 years | $720 | $13,229 | $43,229 |
| 6 years | $641 | $16,179 | $46,179 |
| Figures are illustrative, based on a $30,000 loan at 15.43% p.a. with monthly repayments. They exclude fees and rates aren’t guaranteed. | |||
Are interest rates higher for classic car loans?
Yes, lenders take on more risk with classic cars, which can be harder to value, have a smaller resale market and may not be driven regularly. That risk is reflected in the rate you’re offered.
In the 2025-26 financial year, the average classic car loan rate through Savvy was 15.43% p.a., compared with 12.72% p.a. across all car loans. On a $40,000 loan over five years, that adds about $3,375 in interest.
| Loan type | Average rate (2025-26) | Monthly repayment | Total interest | Total repaid |
|---|---|---|---|---|
| New car loan | 9.80% p.a. | $846 | $10,757 | $50,757 |
| All car loans | 12.72% p.a. | $904 | $14,264 | $54,264 |
| Used car loan | 13.43% p.a. | $919 | $15,137 | $55,137 |
| Classic car loan | 15.43% p.a. | $961 | $17,639 | $57,639 |
| Rates are averages available through Savvy in the 2025-26 financial year. Figures are illustrative, based on a $40,000 loan over five years with monthly repayments. They exclude fees and rates aren’t guaranteed. | ||||
Car Loan Repayment Calculator
Your estimated repayments
$98.62
| Total interest paid: | Total amount to pay: |
| $1233.43 | $5,143.99 |
Case study: financing a classic Torana
Graham has found a restored 1972 Holden Torana for sale privately at $35,000. At 54 years old, it falls well outside the age limit for a standard car loan, so his bank can’t help.
He contacts Savvy, and a consultant compares classic car finance options on our panel. The lender he chooses asks for a professional valuation, which confirms the car is worth the $35,000 asking price.
With a $5,000 deposit, Graham borrows $30,000 over five years at 13.50% p.a. His repayments are $690 a month, with $11,418 in total interest. A three-year term would lift his repayments to $1,018 a month but save him $4,768 in interest.
Graham decides the lower repayment suits his budget better and applies for the five-year loan.
This is an illustrative example. Figures exclude fees, and rates and approval vary between lenders and borrowers.
How to apply for a classic car loan
-
Fill out our simple online application form
Tell us about yourself, your financial situation and the car loan you’re looking for.
-
Submit any required documents
We’ll need to verify your identity and income, so send through necessary docs.
-
Speak to your broker
Your broker will give you a call to walk you through your finance options.
-
Find your car (if you haven’t already)
If you haven’t quite narrowed down the model you’re after, our in-house car broker may be able to help.
-
Get your application prepared
Once you’re happy to proceed, your broker will put your application together for your lender.
-
Receive approval and settle the loan
You can be formally approved from there, after which we’ll settle the deal and the car is yours!
Why apply for a car loan with Savvy?
Fast & easy application
Apply online and submit and sign all your documents digitally. We can assess your profile with a soft credit check, so your score isn't impacted.
Trusted since 2010
With 15+ years of experience and a 4.9-star customer service rating on Feefo, we've helped thousands of Aussies find their ideal car loan.
Unbeatable rates & choices
Access 40+ lending partners nationwide. We compare providers to find the most competitive interest rates tailored to your profile.